Investing in 2026 looks nothing like investing did in the past
Not because the markets have changed. Because you are hit with more information in a single morning than a professional investor received in an entire month twenty years ago.
And here is the trap almost nobody sees:
The same information that should make you a better investor is exactly what can destroy your account.
Access to information is not the same as clarity. It is noise. It is real-time FOMO. It is watching other people’s gains scroll past every three minutes. It is a single tweet flipping convictions you spent a full year building.
Look honestly in the mirror and answer:
How many of you bought into a speculative company just because “it was going up right now” or just because it was trending on X? You became exit liquidity for someone who knew exactly when to sell. Someone who was counting on your excitement.
Do you need an example? Check $SIDU chart
How many of you sold a good position in panic? Not because the thesis broke. Because the red on the screen became unbearable.
Check $AMD chart in March 2025.
How many of you held a core position down 70% with real calm — not resignation, not denial, actual calm — because you knew the business behind that ticker was growing, generating cash, compounding its competitive edge, and the stock price was nothing more than a temporary illusion of collective fear?
That last question is what separates investors from everyone else.
Because in 2026, the edge no longer comes from knowing more than the crowd. Everyone knows. Everyone has access. Everyone sees the same charts, the same news, the same narratives, in the same minute.
The edge comes from enduring longer than the crowd.
From refusing to confuse volatility with risk. From refusing to confuse consensus with truth. From knowing your companies well enough that a 70% drawdown does not change your thesis — it only changes your cost basis.
Markets do not reward the smartest. They reward the most disciplined.
And discipline, in 2026, is the rarest asset on the market.
The takeaway for you: BUY companies that look fundamentally strong, have a strong competitive MOAT, and whose market valuation becomes disconnected from the underlying business — the stock price goes down while the business continues to improve.
During these periods, accumulate and hold the shares for the long term.
September 20 | WEEKEND MINDSET: INVESTING NEEDS A PLAN, NOT PERFECTION
Good morning, Traders and Investors
Because it’s the weekend and there isn’t much market data to analyze — the market has taken a two-day break as well — today I want us to focus on something that may actually be more important than analyzing another stock: mindset, discipline, and having a clear investment plan.
If I had to build a healthy investment journey from scratch, I would start with one simple thing:
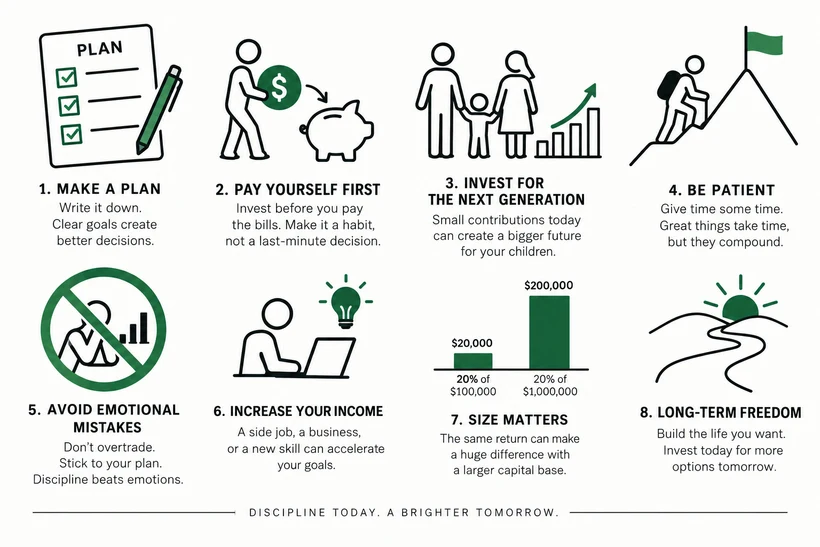
Make a plan.
And I don’t mean anything complicated. Take a piece of paper, old school, and write down:
How much can I invest every month?
What is my target?
How long do I want to take to reach it?
What annual return am I using as an assumption?
What will I do when the market goes down?
What will I do when the market goes up aggressively?
You’ve seen the compound interest calculator I’ve shared with you many times. Use it.
Enter the amount you can invest every month, choose a reasonable annual return assumption, and see what time and compounding can potentially do for your portfolio.
Of course, future returns are unknown. But we still need a framework so we can build a realistic plan.
PAY YOURSELF FIRST
Most people do the exact opposite.
They receive their salary → pay the bills → pay the debt → pay the mortgage → buy groceries → spend money on everything else → and then, at the end of the month, they see what is left for investing.
Very often, there is nothing left.
That’s why I suggest doing something different:
Pay yourself first.
The day you receive your salary, make the transfer to your investment or savings account.
Not at the end of the month.
Obviously, the amount has to be something you can realistically afford. There is no point investing money you need for essential expenses.
Personally, I have always considered 20–40% of a family’s monthly income, where financially possible, an ambitious target for saving and investing.
The important part is this:
Turn investing into a habit, not a decision you have to make every month.
THINK ABOUT THE NEXT GENERATION
Another thing I consider extremely important is building an investment account for your children.
If you have a child who is 1, 2, 3, or 5 years old, time is one of the biggest advantages you have.
You don’t need to start with huge amounts.
You could start with the monthly child allowance, a small recurring contribution, or whatever amount your family can comfortably afford.
This isn’t only about money.
It’s about changing the starting point for the next generation.
If we didn’t have that advantage when we turned 18, that doesn’t mean our children have to start from zero.
Don’t make exceptions every time the market moves in one direction or another.
Because one exception can very easily become a habit.
And long-term investing is, to a large extent, about repeating good habits for a very long time.
And perhaps most importantly:
Be patient.
Give time some time.
You don’t need to constantly buy and sell.
If you own companies you have strong conviction in and your investment thesis remains intact, avoid overtrading simply because you feel like you need to do something.
I have made these mistakes myself.
I sold part of my Palantir position around $30 before it went to $200
I sold part of my Robinhood position around $24 before it went to $100
I sold HIMS around $15 before it went to $70
I sold FROG around $25 before it went to $80
And then?
Some of these companies went on to increase dramatically.
The problem wasn’t only that I sold.
The problem was that I told myself:
“I’ll buy it back lower.”
And sometimes that lower price never came.
DON’T IGNORE YOUR MOST IMPORTANT ASSET: YOUR INCOME
If your current financial situation doesn’t allow you to invest as much as you would like, the solution may not be taking more risk in the market.
The solution may be to increase your income.
A part-time job.
A business.
Turning a passion into an additional source of income.
Learning a new skill.
Anything that can generate additional income that you can then direct toward your financial goals.
Because there is a massive difference between trying to achieve a higher return and being able to invest more money every single month.
MY OWN GOAL
I’m approaching 32 years old, with roughly one month left until my birthday.
My goal for many years has been $1 million. Thanks to this project, I have upgraded my goal to over $2M.
I don’t come from a wealthy family, and I didn’t start with a huge amount of capital. (If I told you that the average salary in my country is around $600, you would laugh or cry.)
I’m trying to build everything on my own.
And if my plan works the way I want it to, my goal is to reach a point around the age of 40 where I have the freedom to decide if, when, and how I want to work.
For me, that’s the real definition of financial freedom.
It doesn’t necessarily mean never working again.
It means not being forced to work simply because you need the next paycheck.
THEN COMES THE POWER OF CAPITAL
Once your portfolio reaches a certain size, the mathematics start to change.
A 20% return on $100,000 is $20,000. (Enough to live for 1 year in my Country)
A 20% return on $1,000,000 is $200,000. (Enough to live at least 5 years with a great lifestyle)
Same percentage.
Completely different capital base.
That’s why, during the first part of the journey, I believe we should focus heavily on:
Contributions + Discipline + Time + Increasing Income.
Later, when the capital becomes large enough, there are more ways to potentially generate cash flow — dividends, options strategies, and other instruments, depending on your experience, risk tolerance, and objectives.
But we don’t need to jump straight to the end of the story.
We need to build the foundation first.
Plan → Contributions → Discipline → Time → Compounding.
That’s what today’s material is really about.
Not what the market will do on Monday.
Not which stock will go up next week.
It’s about you.
About what you can control.
Because the market doesn’t require you to be perfect.
It requires you to avoid making the same emotional mistakes over and over again.
Your Biggest Investing Mistake Isn’t the Stock — It’s Your Behavior
The recurring ones:
Chasing performance. Buying what already ran 200% because it’s “obviously going higher.” You’re usually buying the top of a crowded trade from the people who got in early.
Letting emotion drive entries and exits. Panic-selling the bottom, FOMO-buying the top. The market is a machine for transferring money from the impatient to the patient — most people trade against themselves.
No position sizing or risk plan. Going all-in on one name, or sizing so big that a normal drawdown forces you to sell at the worst moment. How much you bet matters more than what you bet on.
Confusing a great company with a great stock. A fantastic business bought at an absurd valuation can still lose you money for years. Price paid determines your return, not the quality of the story.
Only reading the bull case. Confirmation bias. If you can’t articulate the strongest bear argument against your position, you don’t actually understand the trade — you’re just hoping.
Overtrading. Fees, taxes, spreads, and bad timing quietly eat returns. Most portfolios would do better with less activity, not more.
Refusing to sell losers / anchoring to purchase price. “I’ll sell when it gets back to breakeven.” The market doesn’t know or care what you paid. Holding a broken thesis because you’re underwater is not patience — it’s denial.
Recency bias. Assuming whatever just happened will keep happening — extrapolating a bull run forever, or staying frozen in cash after a crash.
Ignoring what you can’t see. Dilution, insider selling, non-cash “profits,” debt maturities. The headline number is often the least important part.
Following finfluencers without receipts. Taking calls from accounts that only post wins and quietly delete losses. No timestamped track record = no accountability.
The through-line: the biggest edge for most people isn’t a better indicator, it’s temperament, doing the homework, and sizing so you survive being wrong.